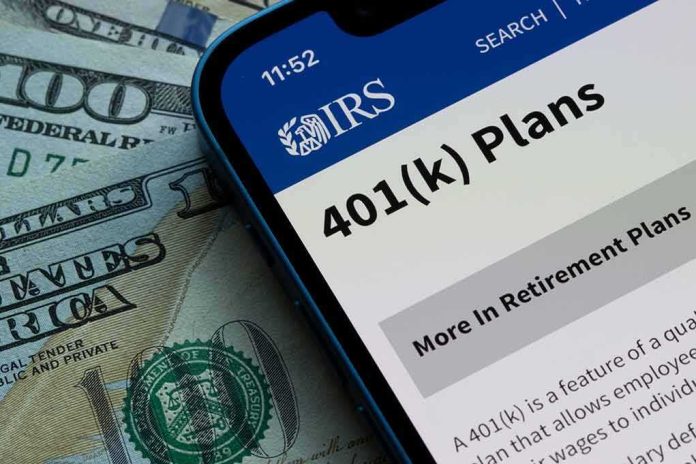
Campaign rhetoric often wraps a real economic signal in a flashy story; here, the signal is straightforward: 401(k) balances do move with markets and contributions, but turning those swings into claims about saving marriages confuses how retirement accounts grow with how relationships actually improve.
At a Glance
- President Trump told rally audiences that wives “fell back in love” after seeing husbands’ 401(k)s surge, citing gains of roughly 58% to 67%.
- The remarks tie personal relationship outcomes to market-linked retirement account growth and credit those gains to Trump.
- Average balances did rise in 2026, though by far less than the eye-catching figures in the anecdotes.
- Household finance research supports a narrower point: financial security and communication lower conflict; a balance spike alone is not a proven driver of affection.
What Trump Said And Why It Landed
At campaign rallies in late October 2026, Trump told supporters he’d heard versions of the same story: a husband shows his wife the latest 401(k) statement, it’s up sharply, and she “loves him again” because she now sees him as a “great investor”—to which he added, “That’s me that did it.” Reported iterations in Rock Hill, South Carolina and Corinth, Mississippi included specific percentages—“60%, 65%, 58%,” and “up 64%” to “67%”—and an instruction to check one’s own account balance as proof of broader economic success under his watch. The anecdote works politically because it collapses a large, abstract thing—the market and economic stewardship—into an intimate, domestic payoff.
The claim has two interlocked parts: first, that many retirement accounts are up materially; second, that these gains translate into improved marital affection, with credit assigned to the president. The first is the easier piece to evaluate; the second requires a different kind of evidence.
How 401(k) Balances Actually Grow
A 401(k) balance changes through three channels that compound over time: the worker’s own contributions, the employer’s match, and investment returns on the accumulated assets. In any given year, all three can matter, and returns are driven by how the account is allocated across equities, bonds, and other holdings; two neighbors can see very different results if one owns a stock-heavy index fund and the other holds stable value or short-duration bonds.
That basic arithmetic makes it plausible that individuals—particularly those with high equity exposure, steady contributions, and long bull-market participation—experience outsized percentage gains over specific windows. It also explains why averages paint a different picture. One widely cited snapshot pegged the average 401(k) balance at roughly $155,800 in the second quarter of 2026, up about 13% year over year—evidence of broad improvement, but nowhere near the mid-60% anecdotes circulating from rally stages. Both statements can be true: averages dampen outliers, while handpicked stories amplify them. The mechanism, however, is contributions plus market returns, not magic.
From Rising Balances To “Saving Marriages”
Financial strain is one of the most consistent sources of conflict in couples; when money stress recedes, arguments often do as well. Decades of family finance research have associated lower financial stress and better communication about money with higher relationship satisfaction, especially in midlife couples who are beginning to focus on retirement readiness. Those studies emphasize habits—saving, spending restraint, debt management, and open discussion—over any single account milestone as the drivers of reduced conflict. It stands to reason that a larger retirement cushion can ease tension. But the literature supports a narrower causal chain than the rally line suggests: it is not the statement’s number itself that creates affection; it is the reduced insecurity and better financial teamwork that track with improved satisfaction.
This is why the anecdote resonates yet overreaches. It captures a real intuition—money worries can erode a marriage and financial progress feels good—while attributing the relational outcome to a market snapshot and a political actor. The stronger claim, borne out by the research base, is more prosaic: consistent participation, prudent allocation, and constructive dialogue reduce financial anxieties that commonly fuel conflict.
Credit And Attribution: Policy Versus Portfolio
Assigning credit for retirement-account gains is not as simple as pointing to who occupies the White House when a statement arrives. Policy can shape growth conditions through taxation, regulation, spending, and expectations, and presidents do influence sentiment. But at the household level, three variables dominate outcomes: contribution rate, employer match structure, and asset allocation—all decisions made by workers and plan sponsors within market cycles that predate and outlast any single administration. Even within a strong equity market, a conservative 401(k) mix will lag an aggressive one; conversely, in a downturn, the conservative approach cushions losses. That dispersion is why campaign anecdotes showcase the winner’s bracket while averages and medians tell a soberer story.
Still, the political point lands: if markets rise broadly, many balances will reflect it. The Fidelity-reported 13% average annual increase in 2026 is an example of a tailwind that a national leader will claim and an opponent will discount. The right question for a saver—and for a couple looking to reduce money stress—is less “who made this balance go up?” than “are we contributing enough, matched efficiently, and allocated appropriately for our horizon?”
The Numbers Gap: Why 13% And 60% Can Coexist
Why do rally stories invoke 60–67% gains when the average is up in the low teens? Measurement window, base effects, and selection. A participant who increased equity exposure during a previous downturn and then rode a multi-quarter rebound can show a dramatic percentage change over that chosen period; include fresh contributions and an employer match, and the balance jump looks even larger. Meanwhile, the average balance statistic is a cross-sectional year-over-year snapshot that blends savers adding new money, retirees drawing down, and wide variation in allocations across millions of accounts. One is a carefully picked slice; the other is the whole orchard.
There is also the difference between return and balance growth. A 64% rise in balance is not the same as a 64% investment return; the former bakes in contributions and matches. Industry papers and plan calculators are explicit on this point, decomposing changes into flows and performance—an essential distinction when comparing sensational claims with steady averages.
What Savers And Couples Can Actually Control
Rally lines come and go; households live with the compounding. Three practices endure across market cycles. First, contribute consistently enough to capture the full employer match; it is an immediate, risk-free return embedded in plan design. Second, align asset allocation with time horizon and risk capacity, rebalancing periodically to avoid drift. Third, turn the account statement into a conversation rather than a surprise—couples who plan together, articulate goals, and define spending and saving rules report fewer retirement-related financial worries and less conflict tied to money.
Sources:
reddit.com, yahoo.com, buzzytimes.com, moneywise.com, scribehawk.com, atlantablackstar.com, onlinelibrary.wiley.com, ici.org, troweprice.com, finexplained.com, pmc.ncbi.nlm.nih.gov